
Three changes to the charitable deduction took effect on January 1 of this year, and the one that will touch the most households is the smallest. Taxpayers who itemize may now deduct only the giving that exceeds half a percent of their income. On $80,000 of adjusted gross income that is $400. On $150,000 it is $750. The money still goes to the charity. It simply stops producing a deduction.
The usual description of this is that the disallowed amount carries forward for five years, and for most households that description is wrong. The statute lets a floored amount join a carryforward only if the taxpayer already has one, which happens only when giving exceeds an annual ceiling of 60 percent of income for cash gifts. A household giving one or five percent of its income never approaches that ceiling, has no carryforward to join, and loses the money permanently. The provision defers nothing for anyone except the very largest donors.
Sponsored by Miso Robotics
Robots Are Seeing Like Humans Now
The gap between humans and robots keeps narrowing every day.
Thanks to a unique NVIDIA collaboration, Miso Robotics just announced cutting-edge 3D-vision for its famous Flippy fry station restaurant robots.
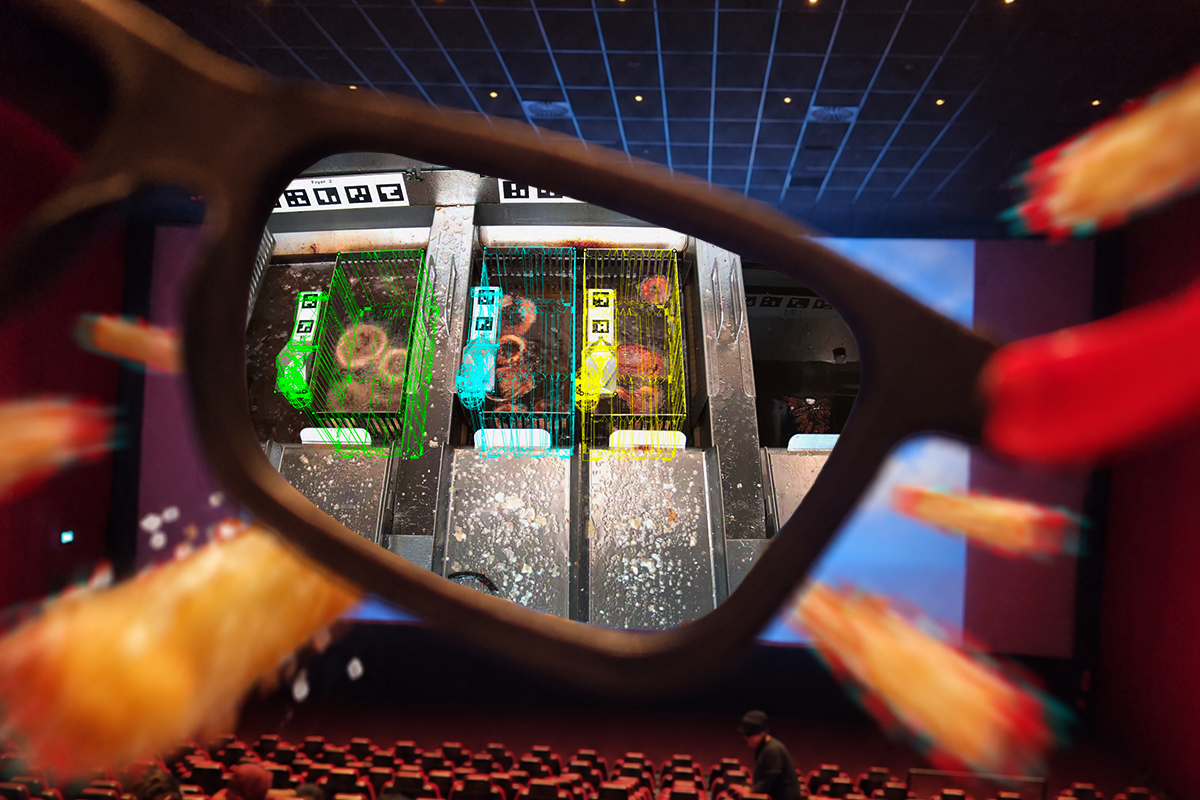
With this upgrade, Flippy is taking its current 2D-vision to the next level, unlocking key advances in safety, operational efficiency, and more. For Flippy users like White Castle, Carl’s Jr., NBA arenas, and college campuses, few things matter more.
Plus, Miso just closed two major asset acquisitions, including a once-SoftBank-backed robotics stalwart. In the process, it even added big-name customers like Jersey Mike’s, Cinnabon, and Auntie Anne’s, and grew its patent portfolio a whopping ~10X.
People have already made 44k+ investments into Miso. This is your chance to claim your own stake in the robot boom.
Get up to 7% bonus stock as a Miso Robotics shareholder today.
What Else Changed
Two other provisions arrived at the same time. People who do not itemize may now deduct up to $1,000, or $2,000 on a joint return, for cash given to a public charity. That amount is not indexed to inflation, applies only to cash, and expressly does not cover gifts to a donor-advised fund or to a supporting organization. It also does not reduce adjusted gross income despite often being called an above-the-line deduction, so it does nothing for Medicare surcharges or for the taxability of Social Security.
The third change trims the value of itemized deductions for taxpayers in the top bracket, which begins at $640,600 for a single filer and $768,700 for a couple. It is not a cap, and for an ordinary retired household it is irrelevant.
The Mechanics of Two Thresholds Instead of One
A retired couple now has to clear two separate hurdles before a charitable gift reduces their tax at all. The first is the standard deduction. For 2026 a married couple both aged 65 or older can take $32,200 plus $1,650 each for age, which is $35,500. Itemizing means beating that number.
The second hurdle sits inside the first. Having cleared $35,500 and chosen to itemize, the couple then loses the first half percent of income from their charitable total. The order matters and is widely reported backwards: the percentage ceilings apply first, then the floor shaves what survives, and anything the floor removes disappears unless a ceiling was already exceeded.
The answer practitioners give is bunching, which means consolidating several years of gifts into one year, itemizing that year, and taking the standard deduction in the others. The reason it works is arithmetic rather than cleverness. The floor is a percentage of income, not a flat charge, so giving five years of gifts at once does not make the floor five times larger. The household absorbs it once instead of five times.
The Vehicle the Law Pushes You Toward
Bunching usually means a donor-advised fund, because few people want to hand a charity five years of support in a single December. A donor-advised fund is an account at a sponsoring charity. The deduction is taken in the year the money goes in; grants out later produce no further deduction. Legal control passes to the sponsor, which may decline a recommendation, and the gift is irrevocable. Federal law sets no minimum payout and no deadline to distribute.
These accounts held $327.9 billion across about 3.6 million accounts in fiscal 2024, granting out $64.6 billion, a payout rate of 25.2 percent against a legal requirement of zero. The average account held $91,300, though most of the recent growth came from very small accounts averaging under $6,000. Fees matter at that size. One large sponsor charges 0.60 percent a year or $100, whichever is greater, so a $5,000 account bunched from three years of church giving pays an effective 2 percent.
What Still Works Without Any of This
The provision that routes small donors toward a donor-advised fund is the same provision that disqualifies a gift to one, so the two new rules pull the identical household in opposite directions depending only on whether it itemizes. For anyone over 70 and a half there remains a route that none of this touches. A qualified charitable distribution moves money directly from an IRA to a charity, up to $111,000 per person in 2026. It is an exclusion from income rather than a deduction, so itemizing is irrelevant, the floor never applies, and because it lowers adjusted gross income it also lowers the floor on any other giving the household deducts. Donor-advised funds and supporting organizations are not eligible recipients. The transfer has to reach the charity by December 31, with no extensions.
America’s New “Subprime” Crisis (Sponsored by Weiss)
Elon Musk’s Next Partnership: Buy This Stock Now (Sponsored by Brownstone Research)
Twice the size of Nvidia – and it's on the move (Sponsored by Brownstone Research)
Should Investors be Bullish on Bullion? (Sponsored by Brownstone Research)
A massive Fed surprise is now underway (Sponsored by Omnia Research)
Green Coffee Company owns its farms outright. (Sponsored by Green Coffee Company)
New Form of AI Could Ignite the ‘Great Wealth Rotation’ (Sponsored by Chaikin Analytics)
How I’m playing the AI melt-up (and down) (Sponsored by Porter & Co.)
DISCLAIMER
The content in this email does not constitute an offer or solicitation to buy or sell any financial instrument. All commentary is general in nature and is not directed at any individual investor.
— John Stone